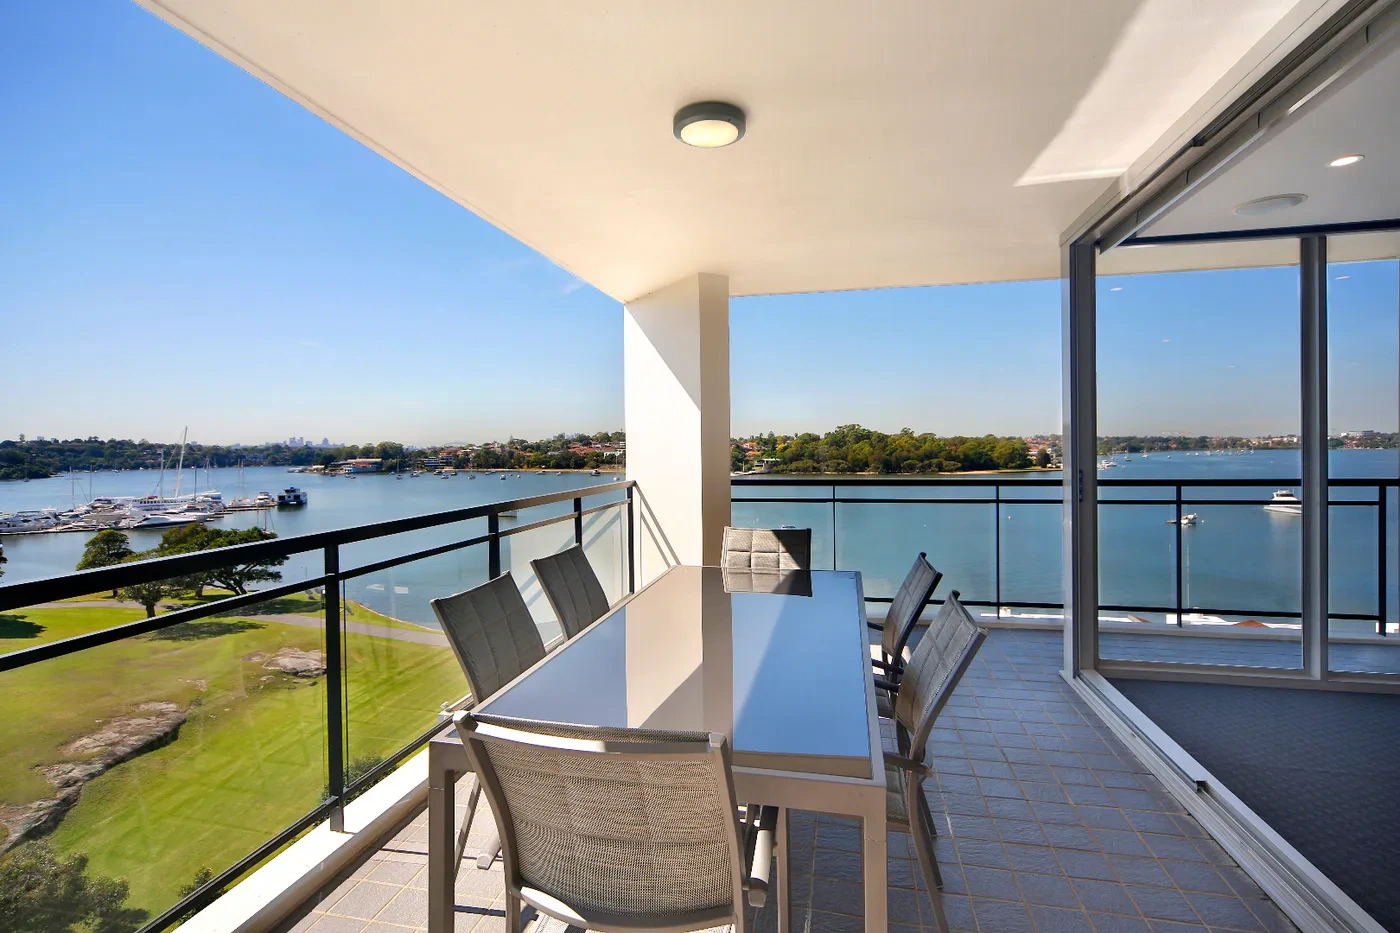
Temporary accommodation after an insurance claim
A repair after water or fire takes months. A rebuild after a storm can run well over a year. If your house is unliveable after fire, flood, storm or water damage, Westprecinct can provide an exquisitely furnished managed serviced residence in Sydney or Melbourne for the months of the repair or rebuild, close to the streets you know. Residences suit whole households, pets are considered on application, and we provide itemised invoices suited to an insurance claim. Melbourne stays are 30 days and beyond, and Sydney stays are for more than three months. We are an accommodation provider, not an insurer or adviser.
When it can’t wait. Tell us what has happened, who is in the household and the suburb you need to be near. We confirm availability as quickly as we can, and we can speak with your insurer, claims manager or loss adjuster directly.
Daily rates for a claim
Every residence shows its equivalent daily rate beside the weekly rate, so a claims manager, loss adjuster or policyholder can set it against the daily or total allowance in a policy at a glance. Both are the 6–12 month rate; higher rates may apply for under 6 months.
Balmain Residence No. 6 · two bedrooms: A$2,275 / week; A$325 / day equivalent (6–12 month stays).
Frequently asked questions
How soon can we move in after fire, flood, storm or water damage?
Tell us what has happened, who is in the household, the suburb you need to be near and the likely length of the works. Many households spend the first night or two in a hotel while the property is made safe. Where a residence is available, we confirm the match and the arrangement in writing, and you can move in as soon as it is confirmed, often within a few days. We can speak with your insurer, claims manager or loss adjuster directly. The stay can continue by arrangement, subject to availability and the guest terms.
My insurer is covering temporary accommodation. Which providers offer furnished residences for one to three months?
Westprecinct provides furnished managed serviced residences in Sydney and Melbourne for households displaced by insured damage. In Melbourne, stays are 30 days and beyond, so one to three months is straightforward. In Sydney, stays are for more than three months, so tell us your expected repair timeline and we will confirm what we can offer. We provide itemised invoices and are happy to speak with your claims manager or loss adjuster.
Where can we live while insurance pays for temporary accommodation in NSW?
Many home insurance policies in NSW cover the reasonable cost of temporary accommodation while your home is unliveable, and the aim is somewhere suited to your household, close enough to keep school, work and routines in place. Your insurer or claims manager usually approves the arrangement, so it is worth asking them to consider a furnished, managed serviced residence rather than a hotel. Westprecinct has residences across Sydney, including Balmain, Rozelle, Drummoyne, Breakfast Point and Barangaroo, with stays of more than three months. We can invoice the insurer, the claims manager or the policyholder directly, whichever is preferred.
What if we need a shorter stay?
Sydney stays are for more than three months. Melbourne stays are 30 days and beyond, so a shorter need is best met in Melbourne. Tell us your dates and we will confirm what is available.
What is temporary accommodation while your home is repaired or rebuilt?
It is a fully furnished, move-in-ready residence to live in while your home is uninhabitable — while damage from an insured event such as water, fire or storm is repaired or rebuilt. Westprecinct provides this across Sydney and Melbourne as a furnished residence, not a hotel room.
How long do people usually need it?
It depends on the works. As a general guide, water-damage repairs commonly run three to six months, while fire and flood rebuilds often take six to eighteen months. Stays are for more than three months in Sydney and 30 days and beyond in Melbourne, with the flexibility to extend as timelines move, which they often do.
How long will an insurer usually cover temporary accommodation?
This is set entirely by your policy, but as general information many home policies fund temporary accommodation for up to around twelve months (some to eighteen), commonly capped at about ten per cent of the home's sum insured. Check your policy and confirm with your insurer or assessor — we can then match a residence and stay length to what applies.
Does Westprecinct work with insurers or a claim?
Guests can come to us while their home is being repaired under an insurance claim. We provide a furnished managed serviced residence and itemised invoices suited to a claim or corporate expense. We are an accommodation provider, not your insurer or adviser — your entitlement and any cap are set by your policy and assessor.
Is it suitable for a whole family, with pets and belongings?
Yes. A Westprecinct residence offers the space, privacy and continuity a household needs — room for the family, a proper kitchen and study, and neighbourhoods with schools and daily life close by. Tell us your household and any specific needs when you enquire.
How is this different from a serviced apartment or hotel?
It is a serviced apartment for extended stays — a real furnished home appointed to The Westprecinct Standard, rather than a compact short-stay serviced apartment or a sealed hotel room. For a stay measured in months while your home is out of action, that difference — space, privacy and a settled routine — is the whole point.
Does home insurance cover temporary accommodation?
Most home building policies in Australia include temporary accommodation cover when your home becomes unliveable due to an insured event, once the claim is accepted. The amount, the time limit and the trigger are all set by your policy — commonly capped at around ten to twelve per cent of the sum insured, for up to about twelve months. This is general information, not advice: confirm your entitlement with your insurer. Westprecinct provides the residence and clear invoices to suit the claim.
My home is unliveable after fire, flood, storm or water damage — can you help quickly?
Yes. When fire, flood, storm or a burst pipe leaves a home unliveable, a hotel room covers the first night, but the repair or rebuild that follows is usually measured in months. We match you to a furnished residence near your suburb so the household stays settled through the works. The stay can continue by arrangement, subject to availability and the guest terms.
Can the whole household move in with our belongings and pets?
Yes. A Westprecinct residence is a full furnished home with the space for the family, a proper kitchen and study, and room for what you bring, and pets are considered on application. Tell us your household, your pets and any specific needs when you enquire, and we match a residence and suburb to suit.
Is this the same as the additional living expenses (ALE) cover on my policy?
Additional living expenses — sometimes called temporary accommodation or loss-of-use cover — is the part of a home policy that funds somewhere to live while your home is unliveable after an insured event. A Westprecinct residence is exactly the kind of genuine furnished home that cover is meant for, and we issue clear invoices suited to the claim. What is covered, and any limit, is set entirely by your policy and assessor; we are the accommodation provider, not your insurer or adviser.
Can you work with our loss assessor, loss adjuster or broker?
Yes. We regularly host guests whose stay is arranged alongside a loss assessor, loss adjuster, broker or insurer. We provide a genuine furnished residence, availability and stay length matched to the works, and itemised invoices suited to a claim — so the accommodation side is simple to substantiate. Your entitlement, approvals and any cap remain a matter for you and your insurer.
Do you offer temporary accommodation in both Sydney and Melbourne?
Yes. Westprecinct provides furnished temporary accommodation across Sydney and Melbourne, in each city's most sought-after suburbs — so you can stay close to schools, work and daily life while your home is repaired or rebuilt. Tell us the suburb you need to be near and we match a residence close by.
What is alternative accommodation on a home insurance policy?
Alternative accommodation is the part of a home policy that pays for somewhere to live while your home cannot be lived in after an insured event such as fire, flood or storm. Some policies call it temporary accommodation or loss-of-use cover. What is covered, for how long and up to what amount is set by your policy, so confirm the details with your insurer. A Westprecinct residence is the kind of genuine furnished home the cover is meant for.
Will my insurer pay for a Westprecinct residence?
That depends on your policy and on your insurer accepting the claim. Many policyholders find that a furnished residence for the months of a repair or rebuild fits their cover, especially where the household includes children or pets. We provide itemised invoices suited to the claim, and we are happy to speak with your claims manager or loss adjuster. We are an accommodation provider, not your insurer or adviser.
What does my insurer usually need for a temporary accommodation claim?
Requirements vary by insurer, but they commonly ask for the accommodation details, the dates, the weekly rate and itemised invoices. Westprecinct can supply a written quote and itemised invoices, and speak with your claims manager or loss adjuster directly. Check your policy and confirm requirements with your insurer.
What if the repairs take longer than expected?
They often do. Your stay can extend as the timeline moves, and we will tell you early if a residence has a limit on how long it is available, so there are no surprises. If your cover has a time or dollar limit, check it with your insurer before extending.
I'm a claims manager or loss adjuster. How do I arrange a stay?
Send us the suburb the household needs to be near, how many people and pets, and the likely length of the works, through the enquiry form or by phone. We confirm what is available, match the residence to the household and handle the stay through one point of contact. We can invoice the insurer, the claims manager or the policyholder directly, whichever is preferred.